
Can Japan win in physical AI?

In 2026, investment in physical AI is surging worldwide. In the United States, single funding rounds exceeding ¥100 billion are no longer unusual. Skild AI, which builds foundation models for robots, raised $1.4 billion in its Series C in January. The Japanese government, too, has set in motion a plan to invest roughly ¥1 trillion by fiscal 2030 in domestic foundation models designed with physical AI in mind.
Measured by capital alone, Japan is clearly at a disadvantage. So what will Japan compete with?
The answer may not be "building the world's best humanoid." Japan has manufacturing floors, robots, sensors, quality control, and a severe labor shortage. In other words, it has a vast "field" where physical AI can actually be put to work.
Perhaps Japan's real opportunity lies less in the robots themselves than in how it brings AI into the workplaces where those robots operate. This article explores that question across global investment trends, domestic players, and national policy.
1. What Is Physical AI? From AI That Answers to AI That Acts
Physical AI is technology that doesn't just "think" but acts on the real world. According to SoftBank, it refers to an entire system in which AI analyzes and makes decisions based on information from sensors, cameras, and other sources, and physical devices then act on those decisions. Generative AI outputs text, images, and code; physical AI outputs physical motion and control signals.
Physical AI works only when three elements come together:
- Brain: Foundation models and VLA (Vision-Language-Action) models that understand situations and decide on actions
- Body: The robots and machines that actually move
- Data: Data gathered from real-world operations that keeps making the brain smarter
If only one of these is present, physical AI doesn't function. And as we'll see, extending this framework to include the workplace itself changes how Japan's position looks entirely.
What Is Happening Globally: Robotics Moves From "Research" to "Real-World Use”
Global investment keeps breaking records. According to PitchBook, robotics and physical AI startups raised $16.3 billion across 492 deals in Q1 2026, a quarterly record. Q2 went further, reaching $18.6 billion across 450 deals. Deal count fell, but deal value rose 25.3% quarter over quarter, setting yet another record. The first-half total came to roughly $34.9 billion.
But the size of the numbers is not what matters most. In its Q1 report, PitchBook observed that robotics is crossing from experimentation into real-world deployment. Investors are no longer asking whether the technology works. They are asking whether a company can manufacture at scale, win paying customers, and bring down integration costs. That is where the evaluation criteria have shifted.
The flow of capital is changing as well. In Q2, momentum reportedly moved toward the "software and components that underpin autonomous systems," including AI and autonomy platforms, actuators and motion systems, and end effectors. Meanwhile, funding for logistics and warehousing fell 68% from Q1. Enthusiasm for humanoids continues, but some experts are cautious. Homes still lack sufficient training data, and many robots still depend on remote human operation. By contrast, structured and predictable environments such as manufacturing are far easier for robots to work in.
That last point carries particular significance for Japan.
Where Does Japan Stand? Behind on Capital, but Holding a Different Card
First, it's worth facing reality. A January 2026 secretariat document for METI's AI Robotics Strategy Council notes that startups in the US and China carry valuations of hundreds of billions to several trillion yen and raise hundreds of billions of yen, while those in Japan top out at tens of billions of yen.
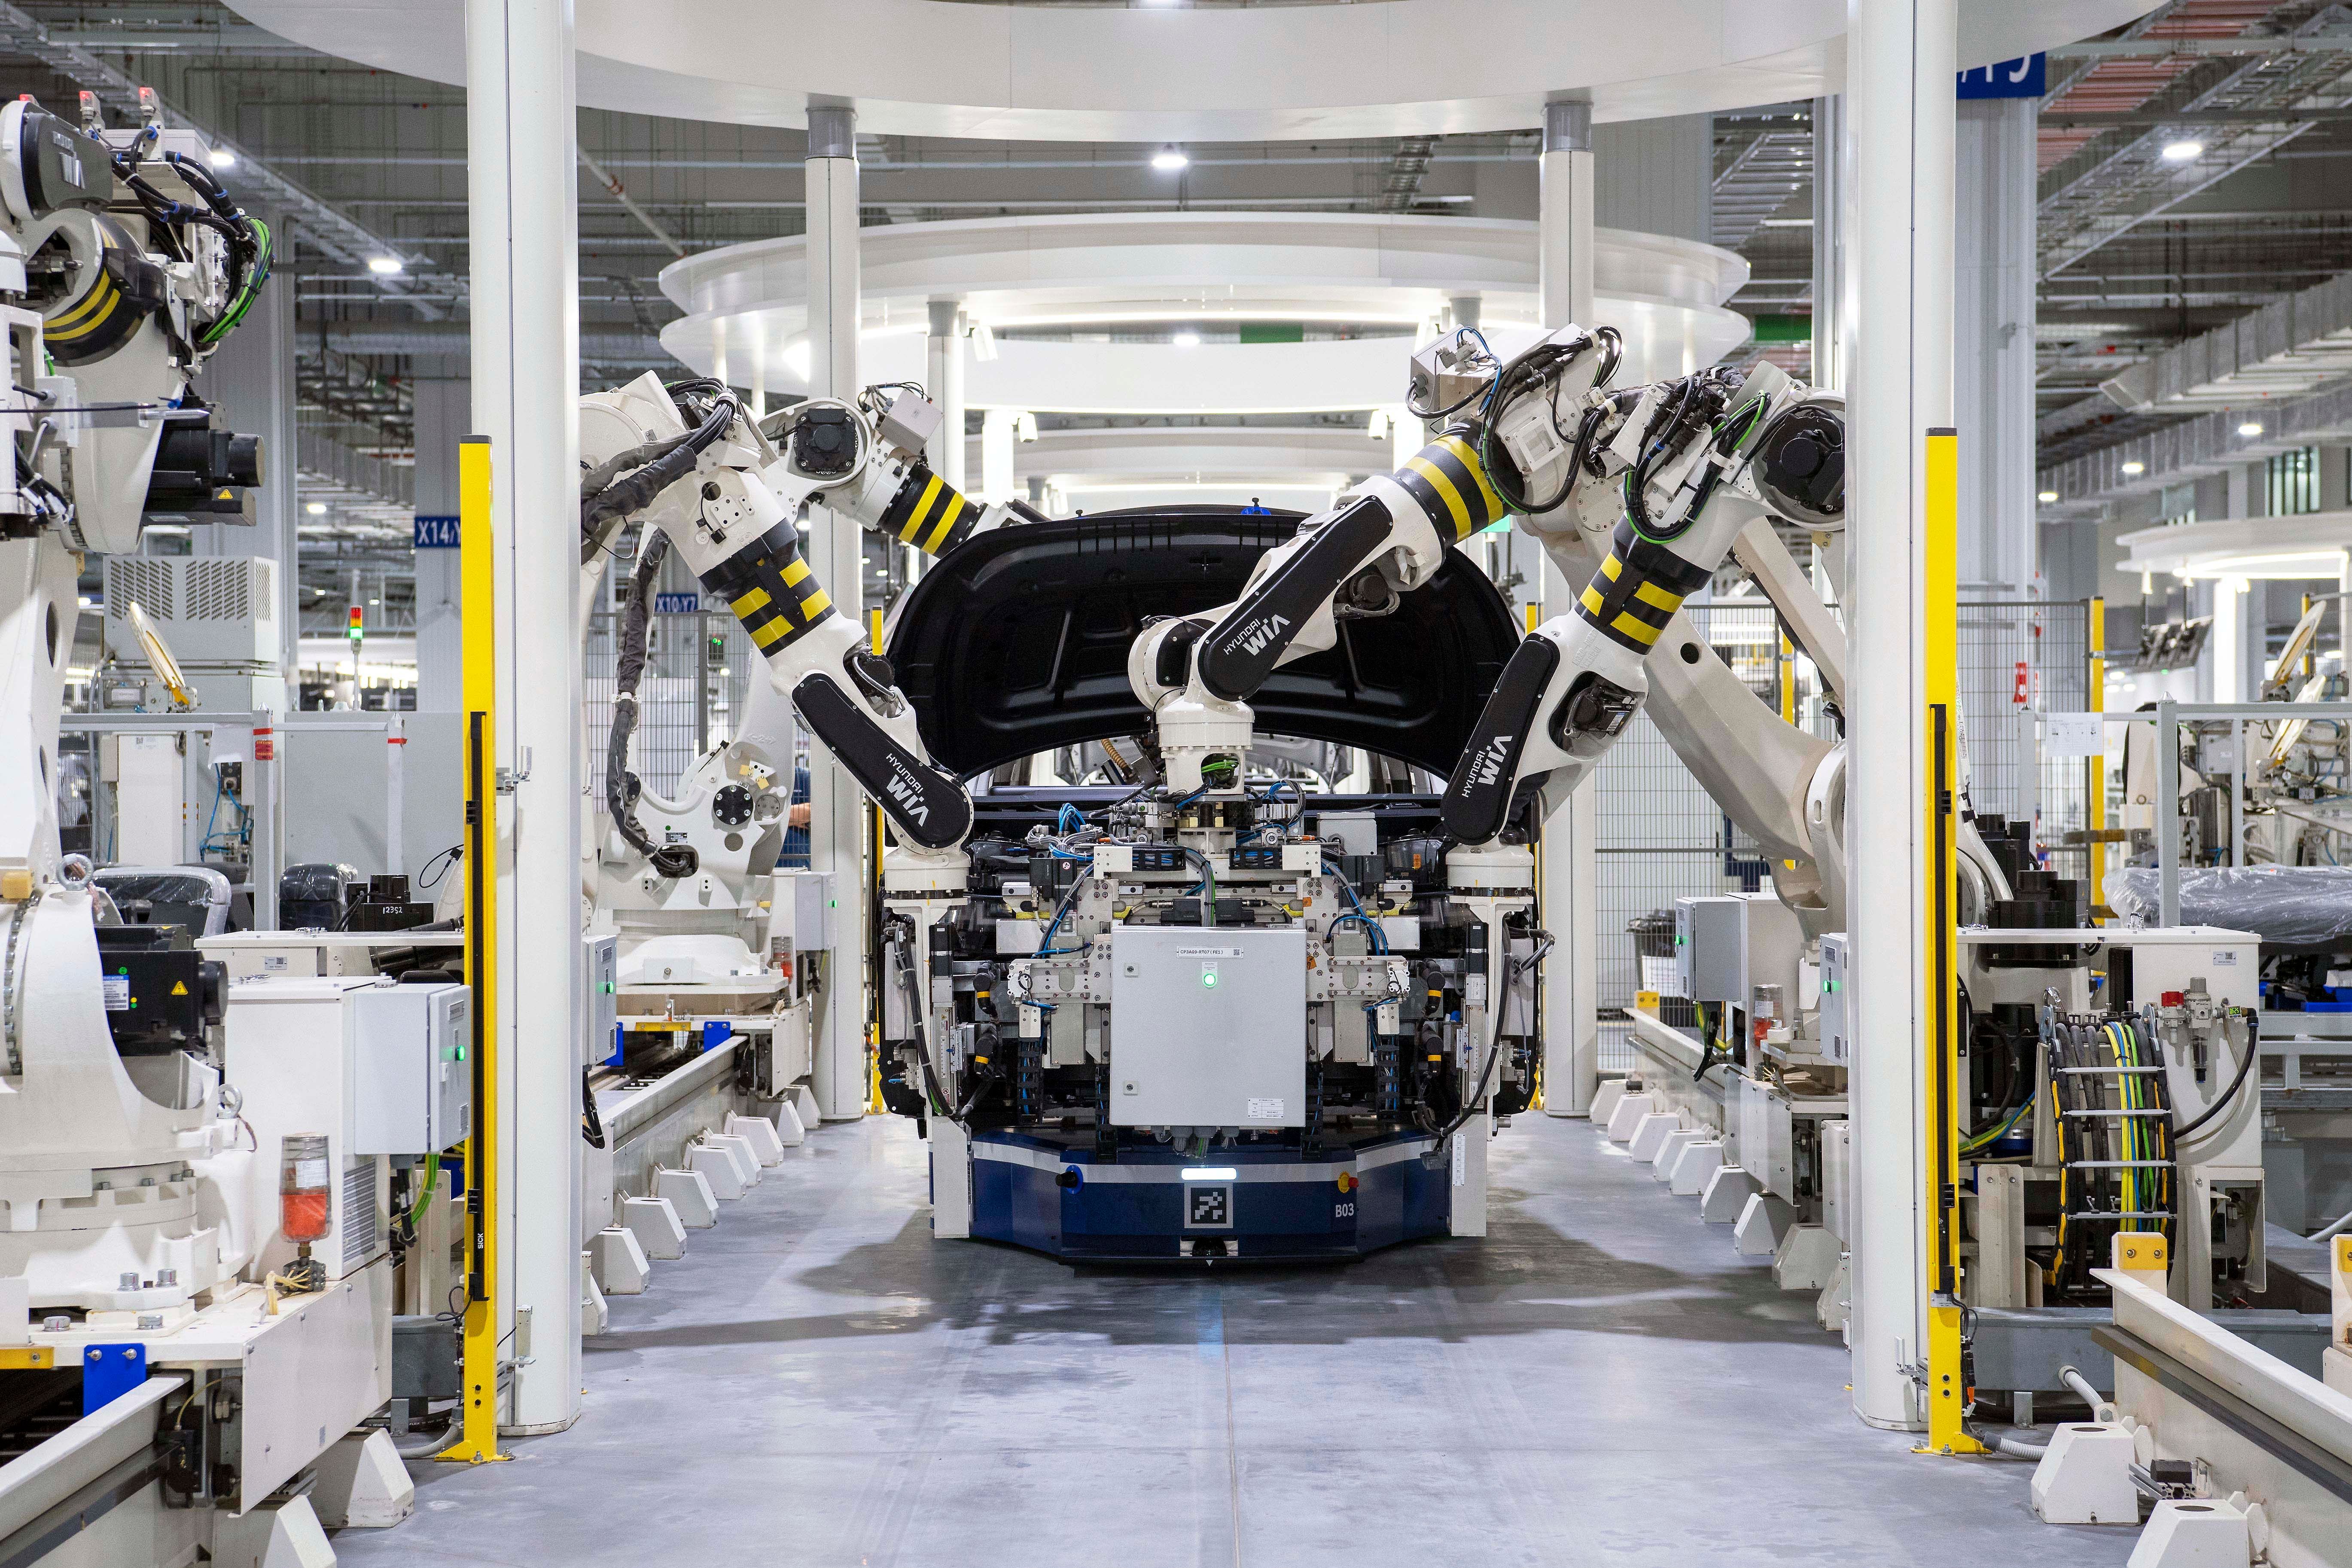
Japan's standing in robotics is not guaranteed either. According to METI, Japan holds about 70% of the industrial robot market. This figure comes from a NEDO survey based on Japanese companies' revenue (2022). Because Japanese manufacturers are strong in high-performance, high-priced products such as large articulated robots, their presence looks overwhelming when measured by value.
Measured by volume, however, the picture changes. According to the International Federation of Robotics (IFR), robots produced in Japan accounted for 46% of global production in 2022, a share that has since fallen to 38%. Chinese manufacturers with strong price competitiveness are rising quickly, and their share of the Chinese market reached 47% by unit volume in 2023. And outside manufacturing, in service robots, Japan trails the US, Europe, and China.
Even so, domestic funding rounds are clearly getting bigger. Mujin is the emblematic case, raising a total of ¥36.4 billion, including debt, in the first close of its Series D. In Nikkei's 2025 startup funding rankings, Mujin and autonomous driving company Turing both placed near the top. Among newcomers, Atom, founded by Turing co-founder Shunsuke Aoki, raised ¥3 billion to develop humanoid AI robots.
Seen as a "robot story," physical AI makes Japan look outmatched by the US and China. But break the competition down into four layers, and the picture changes.
Layer / Key Domestic Players
- Brain: Noetra, AIST, AIRoA
- Robot control/OS: Mujin, Preferred Robotics
- Robots/machines: Atom, RT Corporation, O-ID
- Fields: Operating companies in manufacturing, logistics, food, chemicals, healthcare, and more
Mujin represents the Control layer. Rather than building its own robots, it specializes in software that controls and manages robots from different manufacturers together. Preferred Robotics develops its own hardware, such as the autonomous mobile robot Kachaka, and uses the resulting data to offer a general-purpose AI control platform.
In the Body layer, RT Corporation develops humanoid collaborative robots that work alongside people plating boxed meals in food factories. O-ID aims to manufacture humanoids domestically by drawing on Japan's manufacturing supply chain.
Then there is the layer most discussions of physical AI overlook: the Field. AI creates no value until it enters the workplace.
Look only at the Brain, and Japan is behind. But include Control, Body, and Field, and Japan already holds assets that can compete globally.
The Japanese Government Starts Building the "Brain": ¥1 Trillion for FRONTia and a ¥20.5 Billion Robot Data Platform
The biggest change of 2026 is that the state has seriously begun building physical AI's "brain."
The AI Robotics Strategy, finalized in March, set out to make Japan a "third pole" alongside the US and China. It assumes the global AI robotics market will reach about ¥60 trillion in 2040 and aims for Japan to capture about ¥20 trillion of it, a global share of more than 30%. The June revision added food service and food manufacturing as well as healthcare, expanding the strategy to 18 sectors, and set a target of deploying 10 million AI robots by 2040.
Noetra and AIST are responsible for the Brain. On June 30, METI selected the two as contractors for NEDO's multimodal foundation model development program. First-year funding is about ¥387.3 billion, with the total program expected to reach roughly ¥1 trillion through fiscal 2030. The project is called FRONTia. Noetra has 44 corporate investors, including four core shareholders: Sony Group, SoftBank, NEC, and Honda.
AIRoA is responsible for the Data. NEDO has commissioned AIRoA, whose members include Waseda University and Toyota, to build the data infrastructure needed to develop robot foundation models, committing a total of ¥20.5 billion over fiscal 2025 to 2029. On this foundation, AIRoA has set out a plan to collect about 1 million hours of humanoid manipulation data using more than 100 robots. At the end of July, it publicly released the robot motion dataset AIRoA MoMa 5k, along with a foundation model trained on it.
So why did Japan make physical AI foundation models a matter of national policy? METI's reasoning is straightforward. Leveraging the field data held by Japan's broad industrial base is one of the country's paths to winning, and that requires a domestic model that can put field data to use while keeping it protected.
A clear structure sits behind the national strategy: Brain (Noetra and AIST) + Data (AIRoA) + Field (Japan's manufacturing, logistics, food, and healthcare sites)
The state is building the foundations for the brain and the data. But what ultimately determines their value will be Japan's many workplaces.
Insights
Insight 1: Japan's Greatest Asset May Be Its Fields, Not Its Robots
When thinking about physical AI in Japan, starting from "what kind of robot should we build?" makes the capital gap with the US and China look like a straightforward gap in competitiveness.
Shift the perspective, however, and a different picture emerges. What Japan has built over decades is not just robots. It is the "fields" where robots work, such as factories, logistics hubs, food plants, chemical plants, and hospitals, and the enormous know-how accumulated there.
The strengths Japan has cultivated through industrial machinery and factory automation are high safety and precise motion. As shown, Japanese manufacturers hold a larger share by value than by volume, and that gap is itself a reflection of their quality and reliability. These strengths matter most in tasks where even small mistakes are unacceptable: precision assembly, food plating, pharmaceutical handling, and hazardous work at chemical plants. Kepple has likewise observed that in Japan, rather than pursuing fully general-purpose bipedal models alone, a practical approach of adapting humanoid robots to specific work environments stands out. At GMO's Humanoid Lab, a trial with Asahi Kasei is testing humanoids as replacements for hazardous tasks at a chemical plant.
Japan's other strength is an abundance of sites where such capabilities can be proven. Few countries have such a dense concentration of automotive, electronics, materials, and logistics operations with world-class quality standards. This is reflected in who provides the capital. RT Corporation accepted strategic investments from NSK and DIC, and Noetra has 44 corporate investors. The investors are also the customers, the testing grounds, and the data providers.
AI models can be sourced from overseas. GPUs can be bought. Robot components are available globally. But the data and know-how built up over decades in Japanese factories, about how to work alongside people without accidents and without compromising quality, cannot be easily copied.
Insight 2: Data Over Models. Physical AI Becomes a Race of Learning Loops
When models become commoditized, what is left?
A telling example is the model AIRoA released. It started from Physical Intelligence's publicly released VLA model π0.5 and was further trained on AIRoA's own data. The starting point for the brain, in other words, still lies overseas.
Even so, value comes from the data built on top of it. That includes task data from real sites, robot manipulation data, simulation data for Sim-to-Real, performance and safety evaluation data, and operational data collected after deployment.
The key is not to collect data once and stop.
The "Learning Loop" That Defines Competitiveness in Physical AI:Model → Deployment → Data → Better Model → Deployment …
Deploy the model on site, gather data from the site, improve the model with that data, and send it back into the field. The government's policy package likewise aims to rapidly cycle field data accumulation and AI model improvement so that demand and supply expand together.
The question in physical AI is not whether you can build the best model once. It is how fast you can run the loop of collecting data from the field, improving the model, and sending it back.
Insight 3: From Demo to Deployment. The KPIs of Physical AI Are Changing
In physical AI, how many units are running in the field is becoming more important than model performance.
As noted earlier, global investors are shifting their criteria from "does the technology work?" to manufacturing at scale, customer acquisition, and integration costs. Mujin is an early example of this in Japan. MujinOS has been deployed in more than 2,000 cases worldwide, and most of these are reportedly in live production rather than proofs of concept.
When evaluating physical AI startups going forward, what matters is not how impressive the demo video looks. It is units deployed, operating hours, revenue per unit, hours of human labor replaced, accident rates, human intervention rates, retention, and recurring revenue from models such as RaaS (Robotics as a Service). With so many sites available, Japan is well positioned to build this kind of operational track record.
6. 2027–2030: Four Checkpoints for Japan's Physical AI
Rather than predicting the future, it is more useful to lay out what to watch.
① Can domestic models actually move robots?
The foundation model developed by AIRoA is scheduled to be made available as open source around June 2027. FRONTia aims for "real-world native AI" that understands physical properties such as spatial awareness by fiscal 2030. What matters is not benchmark scores but actual performance in the field.
② Can Japan accumulate usable data?
Volume alone is not enough. The question is whether the data captures on-site failures and edge cases, and whether it genuinely improves the models.
③ Can Japan move from PoC to production?
The question is not "we ran a pilot." It is how many units ran, for how many months and hours, and with how little human intervention.
④ Can technology forged in the Japanese workplace go global?
Will this end with easing Japan's domestic labor shortage? Or can robots and software refined in Japan's demanding environments be exported worldwide? The key is whether more companies follow Mujin in expanding deployment globally.
Not the World's Best Robot, but the World's Most AI-Enabled Workplace
The race in physical AI is not only about who builds the smartest AI. It is also about who gives AI a body, who sends it into the field, and who can feed the data generated there back into the next AI.
In that sense, Japan still holds a major card: world-class manufacturing sites, combined with the intense demand created by a labor shortage.
In 2026, Japan's physical AI race has only just begun. The question is not whether Japan can build the world's best robot. It is whether Japan can turn its workplaces into the most AI-enabled workplaces in the world.